Industrial Market Update: Inland Empire Q4 2025
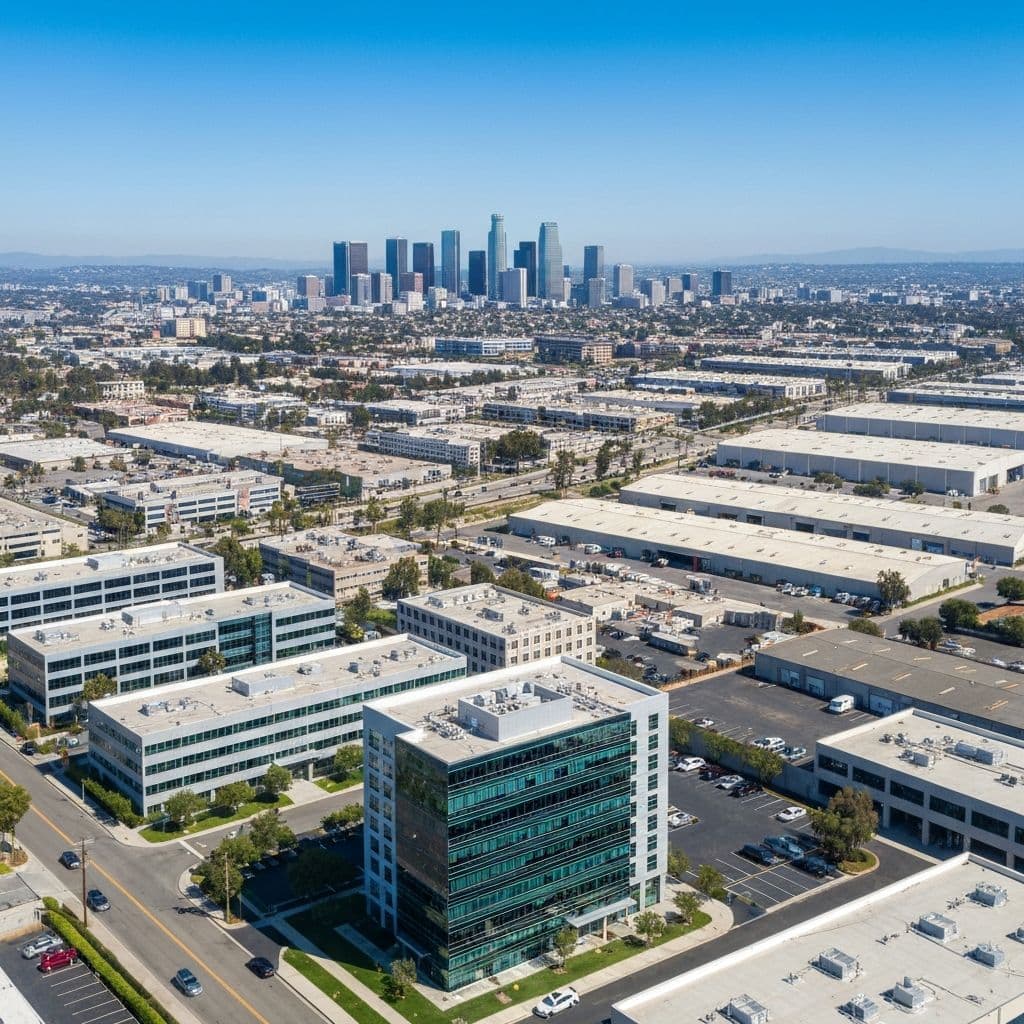
The Inland Empire remains the largest and most closely watched industrial market in the country, and Q4 2025 reinforced why. While net absorption has settled well below the extraordinary pace of 2021, the fundamentals underpinning the market — proximity to the ports of Los Angeles and Long Beach, freeway access via I-10, I-15, and SR-60, and a labor pool that continues to grow — remain intact.
Vacancy across the region ticked up modestly as a wave of speculative development delivered in 2023 and 2024 finally worked through lease-up. That said, the increase has been concentrated in large-format big-box product (500,000+ square feet), while mid-size buildings under 150,000 square feet — the space favored by regional 3PLs, last-mile delivery operators, and light manufacturers — have held vacancy in the low single digits.
Rental rates have stabilized after two years of correction from their 2022 peak. Landlords with well-located, functional buildings are no longer chasing the market down; instead, we're seeing rate discovery settle into a range that both sides can transact on, which is translating into a healthier pace of lease signings heading into 2026.
On the investment sales side, cap rates for well-leased industrial assets in core Inland Empire submarkets have compressed slightly from where they sat a year ago, as debt costs have eased and institutional capital has returned to the market looking for stabilized yield. Value-add and owner-user opportunities — particularly smaller yard, storage, and flex buildings — continue to see the most competitive bidding, since they attract both investors and users who need their own space.
For owners considering a sale or refinance, and for buyers looking to place capital in what remains America's premier logistics market, now is a good time to get a current read on where your specific submarket and building type stand.
Have Questions About Your Property?
Our team is available to discuss your specific situation — no obligation.